New Construction
Buying New Construction in Kansas City in 2026: The Monthly Cost Story
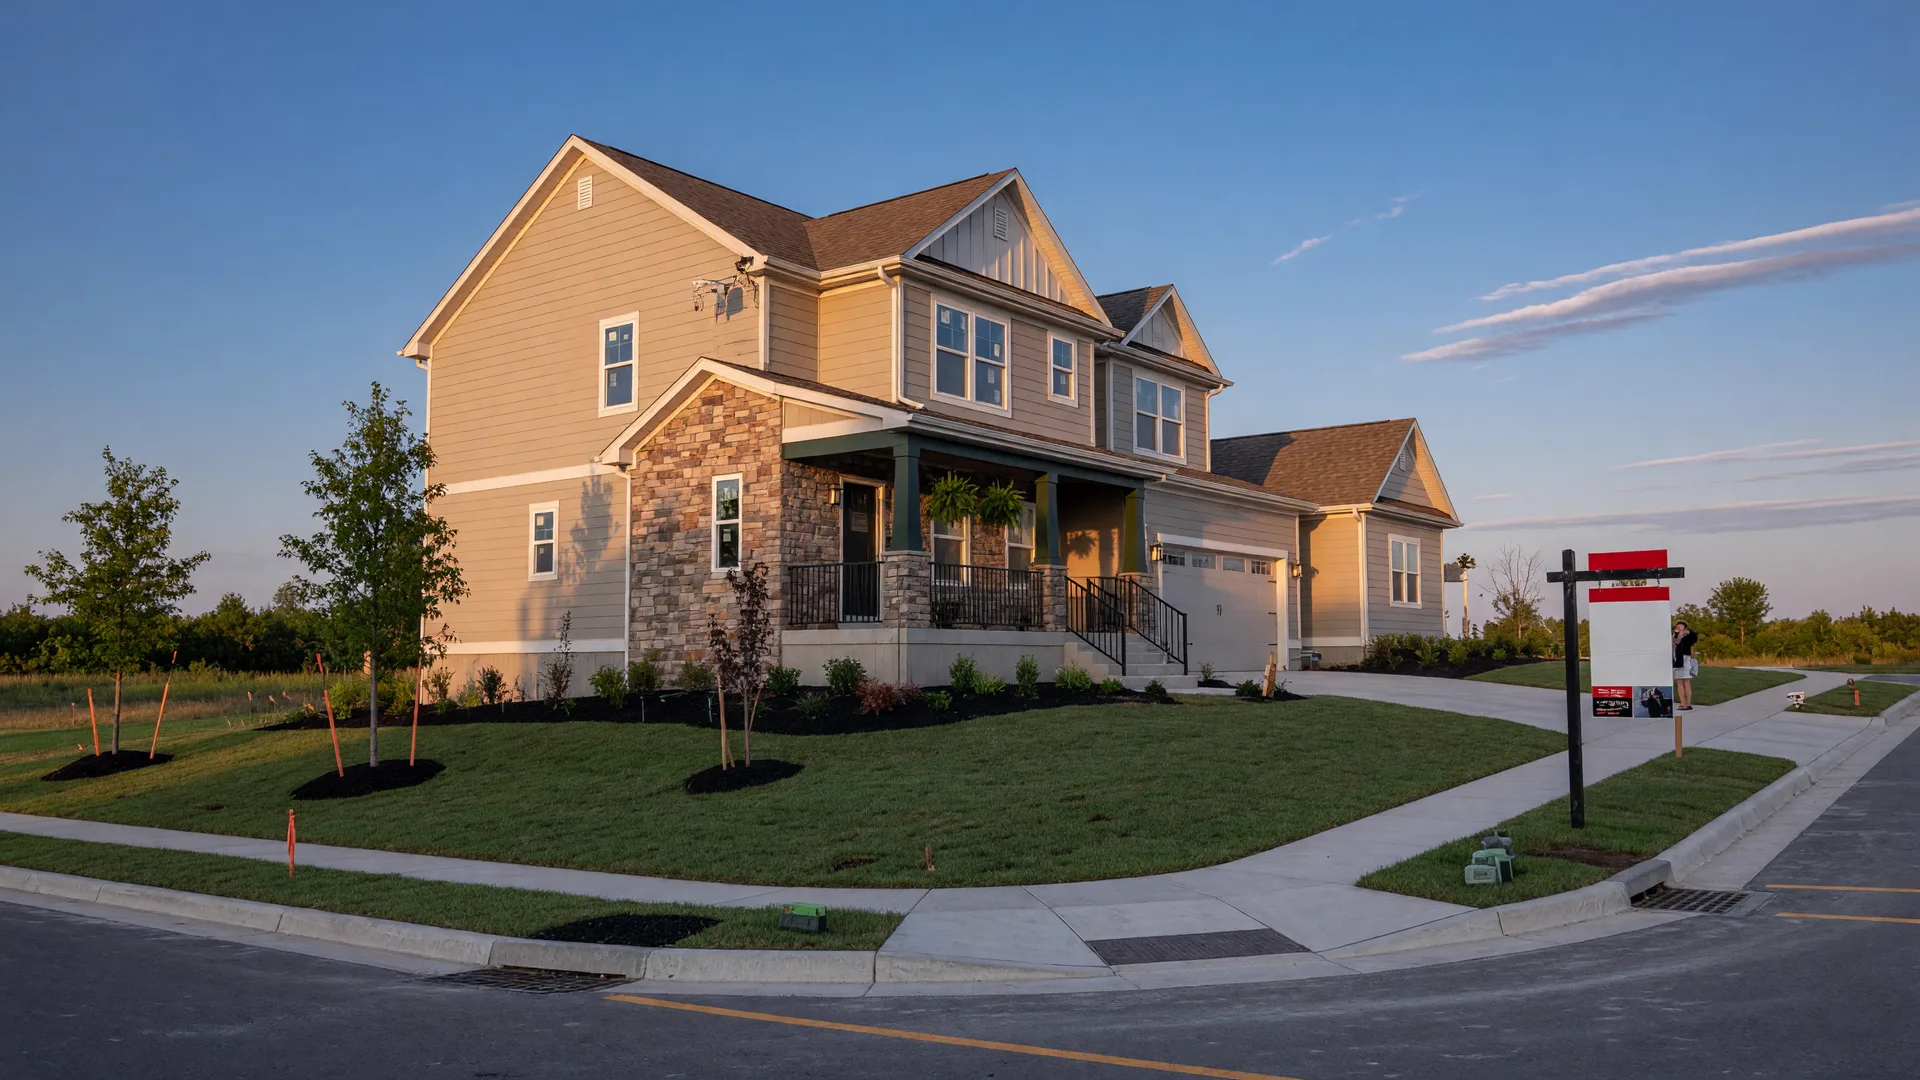
For years the assumption was simple: building a new home costs more per month than buying an existing one. In late 2026, that assumption no longer holds in many parts of the Kansas City metro. With mortgage rates hovering near the mid-6% range and builders stacking incentives on top of price, the monthly payment math has changed, and it is worth a closer look before you buy.
As a builder, renovator, and real estate advisor, Jason sees both sides of this comparison every week. Here is how the late-2026 Kansas City new construction market actually shakes out, and how to compare it fairly against an existing home.
The Late 2026 Kansas City Market, by the Numbers
The Kansas City Regional Association of REALTORS mid-year review, released in early August 2026, shows a metro that is still competitive. The median sale price was $349,110, up 4.5% year over year. Homes spent a median 25.5 days on market, and about 30% of homes sold above original list price. Inventory sat at about 2.2 months of supply. In plain terms, resale is still a seller-friendly, competitive market where good homes move fast and buyers often pay close to asking.
That is exactly why new construction is attracting more attention. A new home is priced once, has a fixed timeline, and comes with builder incentives that existing homes do not offer. When resale is competitive and prices are near asking, the available inventory at a builder's site can look like a welcome alternative.
Why Incentives and Rate Buydowns Shift the Math
Forecasters expect the 30-year fixed mortgage rate to stay near 6.3% to 6.5% through the end of 2026 rather than dropping sharply. To keep payments workable, builders across the Kansas City metro are pairing price with mortgage rate buydowns, often 2-1 or 3-2-1 structures paid by the builder, plus closing cost credits and design credits. Across the metro, new construction incentives average roughly 5% off the purchase price.
Here is where it gets interesting. When you finance an incentived new home at a bought-down rate, the monthly payment in many communities, including outer suburbs like Grain Valley and Oak Grove, comes in below buying a comparable resale home at the prevailing market rate. List price alone never tells you that story. Only the monthly payment does.
Focus on the monthly payment, not the list price. A rate buydown can lower your payment for the first two or three years, and a well-timed refinance can make that a permanent win. We compare the full financed cost on every new construction option so you see the real number.
How to Compare New Construction vs Resale Like a Builder
To make a fair comparison, lay out four things side by side: the price after any incentives, the financed monthly payment at the rate you are actually quoted, the warranty and maintenance picture, and the energy efficiency of the build. A new home comes with a structural warranty and modern insulation and windows, which can mean lower repair and utility costs in the early years. An existing home may have charm and a mature lot, but it often carries deferred maintenance you will pay for later.
Be sure to price the true costs of new construction too, not only the base price. Lot premiums, structural options, upgrades, landscaping, and closing costs all add up, and they affect your payment. When you compare the honest total against a resale home you plan to update anyway, new construction is far more competitive than most buyers assume.
Next Steps for Kansas City Homeowners
There is no single right answer for every buyer, which is why we sit down and run the actual numbers for each community and builder. If you are weighing new construction against an existing home this fall, bring us your floor plans and builder quotes and we will compare the true monthly cost, the incentives, the buydown, and the resale value together. Schedule a free consultation or call us at 816-533-3100. We help you build smarter and buy with confidence.